

In recent global markets commentary, the specter of a so-called “capital war” has been raised with renewed force, largely via warnings from high-profile investors about what may lie ahead if geopolitical tensions escalate. Ray Dalio, founder of Bridgewater Associates and one of the most watched voices in macro investing (a legendary figure), has framed the risk as something deeper and more enduring than mere trade or tariff disputes. According to Dalio, capital wars represent a stage of international conflict in which money itself becomes a coercive weapon, where countries might reduce appetite for each other’s debt, sever financial linkages, or even weaponize financial assets in ways that undermine economic stability and geopolitical trust. This idea has captured attention because it shifts the focus from goods and tariffs to the very infrastructure of global finance. This argument closely parallels the discussion we had roughly two weeks ago regarding the (im)possibility of weaponizing US Treasuries. What is notable, however, is that an increasing number of commentators continue to raise this scenario, despite the fact that, in my view, it functions more as a conceptual boogeyman than as a concrete financial reality. In the following, I will explain why I do not believe we are in the midst of a “capital war”, or anything resembling one (I might be wrong, of course, but this is how I see it).
In more detail, the marketing of this “capital war” framing suggests that nations could actively use capital flows, asset holdings and/or reserve positions to coerce rivals or protect themselves, potentially causing dramatic shifts in global investment patterns. Dalio’s commentary points to historical precedents in which economic and financial coercion preceded traditional military conflict, and to contemporary market responses, including surging gold prices and repositioning by some institutional investors, as early evidence of a shift in sentiment.
But despite the appeal of this narrative, the underlying reasoning is deeply flawed in its analytical foundations. The idea of a capital war abstracts the mechanics of finance into a geopolitical tool without sufficiently confronting the structural realities of the global monetary system. It merely conflates correlation with causality, and it underestimates the robustness of existing financial infrastructure, particularly the centrality and resilience of the US dollar system, and the incentives faced by sovereign and private holders of capital. A careful examination shows that what Dalio calls a capital war is mostly a repackaging of well-known trends, such as diversification of reserve portfolios, responses to sanctions, geopolitical risk premiums in specific commodities and so on, not necessarily evidence of an inevitable system-breaking conflict.
To understand why this matters, one must first recognize that warnings about capital wars typically start from the premise that capital flows and reserve holdings are easily weaponized. In Dalio’s framing, when geopolitical relations deteriorate, the logic goes, investors (including sovereign holders) will reduce their exposure to perceived adversaries’ assets, particularly sovereign debt, thereby inflicting economic pain. It is asserted that even allies would become reluctant to hold each other’s debt in times of conflict, preferring “hard currency” or other assets outside governmental control to traditional sovereign bonds (think about gold and silver again).
But this premise ignores both the incentives and institutional constraints that govern how capital actually moves. First, what is often described as a shift away from US debt (because this is what it is all about…) in response to geopolitical stress tends to be incremental and cyclical, not sudden and structural. Sovereign and private investors adjust portfolios based on risk-return trade-offs, maybe liquidity needs, not solely geopolitics. There is little evidence of coordinated or systemic sell-offs of US Treasury securities by central banks in recent history, even during periods of meaningful geopolitical strain (this is something I also discussed in this post). In fact, when risk aversion rises, demand for US Treasuries typically increases because they remain the deepest, most liquid safe asset globally. This pattern contradicts the idea that geopolitical tension leads directly to asset abandonment. Rather, it reflects flight-to-quality behavior that benefits the US sovereign market in times of stress.
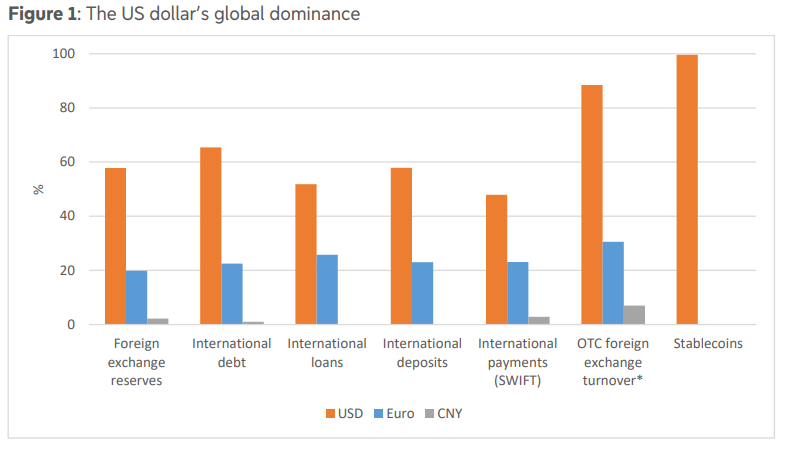
Source: European Parliament
Second, the concept of capital wars assumes a level of fungibility and policy control over capital flows that simply does not exist at scale. Countries and institutions cannot readily “dump” assets like Treasuries without incurring significant market impact and self-inflicted losses (I’ve discussed the reasons here). Financial markets are not static repositories of capital to be deployed at will. If you want, they are dynamic systems in which massive, uncoordinated sales would depress prices and raise yields, hurting the seller’s own balance sheet before inflicting meaningful strategic pain on targeted economies. Even if a government wanted to weaponize $2 trillion in Treasuries, there is no alternative market of equivalent depth and liquidity ready to absorb the flows, a point confirmed by analyses of Treasury holdings and global safe asset markets. The systemic role of Treasuries as collateral and liquidity anchors means that aggressive selling would create self-harm rather than leverage.
Third, warnings about capital wars often fail to recognize the institutional mechanisms that mitigate systemic stress. Central banks and international authorities have a range of tools, from swap lines to coordinated liquidity facilities, that stabilize liquidity and funding markets even under duress. The Federal Reserve’s standing swap arrangements with other major central banks, for example, were activated during global crises precisely to ensure the continued flow of US dollar liquidity, not to shield US authorities from foreign coercion. These mechanisms have dampened the very feedback loops that “capital war” scenarios assume would manifest abruptly and violently.
A second layer of critique comes from a deeper understanding of what money and capital actually are in the modern system, an understanding that is often obscured by geopolitical metaphors like “war”. Ok, I am not suggesting that Ray Dalio is unaware of these dynamics. Rather, the issue may be an overreliance on textbook econometric models that abstract away from how the global financial system actually functions in practice.
But in technical (but also practical) terms, a global monetary economy based on fiat money and extensive banking intermediation is not primarily about static piles of sovereign bonds that can be switched on and off like strategic resources. Rather, it is about the continuous creation and destruction of credit and money, much of which occurs outside formal sovereign balance sheets through bank lending and offshore dollar markets such as the eurodollar system. This system, which allows USD-denominated liabilities to proliferate internationally through banking and shadow banking networks, means that the monetary base is far larger and more elastic than simple reserve holdings would suggest (there are so many articles and books on this system, maybe you can start with this one). The creation of credit through private banking means that markets are governed by endogenous liquidity conditions rather than exogenously fixed stocks of capital.
From this perspective, the real “war on fiat” that some analysts warn about is not a geopolitical confrontation between sovereign reserves, but a contest over the perception and function of money itself. This is the argument advanced by commentators who view the eurodollar system as central to understanding monetary dynamics: modern money is not a passive asset owned by states, but a set of promises and credits continuously negotiated across banks, firms, and households (on different hierarchical layers, thanks Perry Mehrling). Risk in this system is endogenous, driven by shifts in leverage or liquidity conditions, not by geopolitics alone. That analytical lens casts Dalio’s capital war narrative in a different light. For example, what appears to be geopolitical conflict over sovereign assets may actually be structural adjustments in how money is created (and used) in markets.
This is why the US dollar has not experienced significant disruptions. For instance, just last month it was reported that the USD global transactions use jumps to new high. Likewise, the Treasury Department’s November 2025 report showed that foreign holdings of US Treasuries reached an all-time high of $9.355 trillion in November, up from October's $9.243 trillion. Compared with a year earlier, Treasuries owned by foreigners were up 7.2% in November. More than that, overall net foreign acquisitions of US long-term and short-term securities and banking flows amounted to a net inflow of $212.0 billion. Of that total, net foreign purchases of long-term US securities were $221.8 billion, and foreign official institutions alone were net buyers of $64.0 billion in long-term US securities. Although the net change in short-term holdings (Treasury bills) was smaller, this data confirms that foreign entities are still investing in US assets rather than abandoning them. More than that, data from the IMF’s COFER database show that the share of the US dollar in allocated global foreign exchange reserves remained near historical norms in 2025, with around 56–57 % of disclosed reserves still held in dollars. A stable dollar share in official reserves, even amid geopolitical stress, argues against wholesale de-dollarization. And even if it may not seem directly related, all of these dynamics ultimately tie back to the way the eurodollar system governs global financial relationships. A country cannot wage a true “capital war” against another that provides the very infrastructure on which global finance relies, no matter how many political narratives are invoked.
It is precisely this eurodollar framework that brings me to the point concerning the historical examples often cited to justify fears of a capital war. Dalio has pointed to episodes such as European pre-World War I financial restrictions and modern sanctions against Russia, Iran, and North Korea as historical precedents where capital was used coercively. While such episodes involved financial pressure (or weaponized interdependence, how it was called in the literature), they occurred in specific contexts that cannot be generalized mechanically to the US Treasury market today. Those cases often involved relatively closed financial systems and targeted sanctions against smaller economies. In contrast, the US Treasury market is the largest, most liquid, and most globally embedded sovereign market in existence, and its role as the cornerstone of international finance remains intact. There is no comparison.
Critically, the very attributes that Dalio identifies as vulnerabilities, the USD dominance, high foreign holdings of Treasuries, the centrality of US financial markets and so on, are also the reasons why systemic rupture is unlikely. Deep markets with broad global participation are inherently harder to weaponize because many actors have conflicting incentives and diversified portfolios. Sovereign holders such as central banks do not rebalance in isolation. Most of the time, they operate within a web of financial and political objectives that favor gradual, risk-managed adjustments rather than abrupt disinvestment. Let’s take the ECB as an example. Does anyone seriously believe that a central bank of this kind, regardless of whether public or political pressure were ever to intensify, could sever all forms of engagement with the US dollar, whether in the form of asset holdings or swap line arrangements? Such an outcome is both a logical and a financial impossibility, particularly given the profound degree of dollarization embedded in the European banking system.
Another (or the last) flaw in the capital war narrative is the implicit assumption that sovereign debt holdings are levers of political influence in a zero-sum game. This assumption overstates the political control sovereigns have over private international capital and underestimates the role of private sector incentives and market liquidity. Foreign buyers of Treasuries, including pension funds, mutual funds, insurance companies, private investors etc., are driven by risk management and portfolio diversification, not by alignment with sovereign geopolitical strategy. Their behavior cannot be reduced to simple political alignment or opposition.
The capital war framing also obscures a more important point. The stability of the global monetary order ultimately depends more on confidence in the underlying institutions and network effects of money. Currencies gain and retain international roles because they are useful in trade, payments, invoicing, and as a store of value, not because one country holds another’s debt. Network effects and liquidity advantages mean that once a currency like the dollar is entrenched, it is extremely hard to dislodge except through prolonged systemic breakdowns, which are themselves rare.
In short, the idea that the world is on the verge of a capital war, where geopolitical tension transmutes into financial conflict of existential proportions, is a dramatic narrative that obscures more than it clarifies. It takes structural phenomena that are already well understood within monetary economics and reframes them in militaristic terms that appeal to intuition but lack analytical precision.
This is not to dismiss legitimate questions about reserve diversification or even the long-term sustainability of fiat systems, but it is to caution against conflating these issues with an imminent capital war that markets and policymakers are powerless to prevent. A more grounded approach recognizes that capital flows are shaped by a complex set of incentives, regulations, and market structures where no single actor can unilaterally weaponize money at scale without significant self-impact.
Excellent overview Alexandru, well reasoned and comprehensive. Saves me a lot of trouble. Was planning to write a similar counter point to Dalio. His constant hysterics have grown tiresome. He takes whatever market theme prints over the previous quarter and attempts to repackage it as the next crisis, or as further evidence of his perpetually-delayed world crisis view. First it was an 'everything bubble', then it was a 'debt armageddon', now it is a 'capital war'.
Great article, and much appreciated pushback on over-baked historical comparisons. The dollar flywheel is not slowed easily. A couple of questions:
- Would derivatives (eg credit default swaps) amplify harm to a country intent on weaponized selling?
- In the event of a foreign country sovereign bond default (eg, Britain), is this analysis impacted?
- Does major US recession or geopolitical dislocation (eg, war with China) have any impact?
Apologies, just looking for where the black swans are located.